|
Key Insights
|
Details
|
|
Forecast Period
|
2027-2031
|
|
Market Size (2025)
|
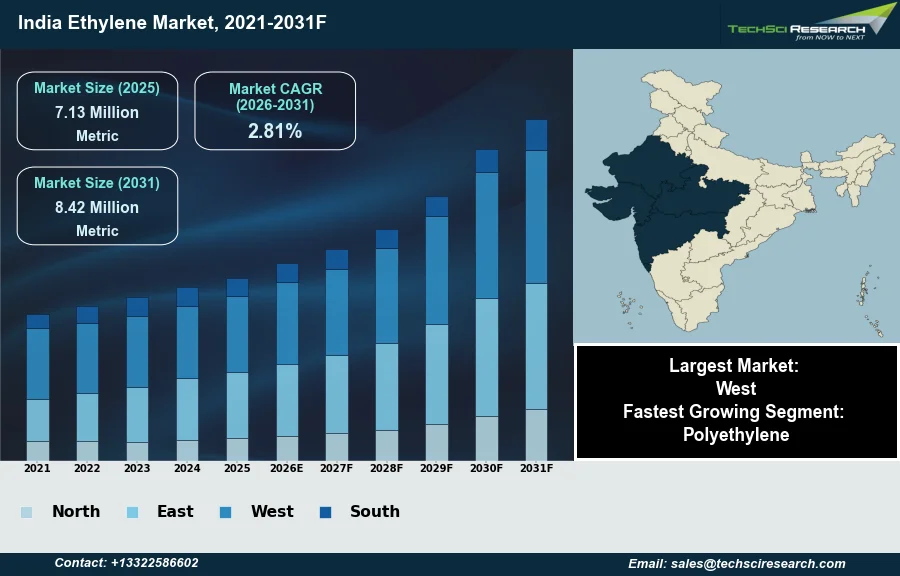
7.13 Million Metric Tonnes
|
|
CAGR (2026-2031)
|
2.81%
|
|
Fastest Growing Segment
|
Polyethylene
|
|
Largest Market
|
West
|
|
Market Size (2031)
|
8.42 Million Metric Tonnes
|
Market Overview
The India Ethylene Market is expected to grow from 7.13 Million Metric Tonnes in 2025 to 8.42 Million Metric Tonnes by 2031 at a 2.81% CAGR. Ethylene, a fundamental organic hydrocarbon (C₂H₄) primarily produced through steam cracking, serves as a crucial building block in the petrochemical industry for manufacturing various derivatives, including plastics like polyethylene, ethylene oxide, and ethylene glycol. The Indian ethylene market experiences growth driven by robust demand from diverse downstream sectors, such as the expanding packaging industry, increasing consumer goods production, and various industrial applications including textiles and automotive components. Government initiatives to bolster the petrochemical sector and significant infrastructure development further contribute to market expansion.
A significant challenge impeding market expansion is the inherent volatility in crude oil prices, which directly impacts feedstock availability and production costs for ethylene manufacturers. According to the Department of Chemicals and Petrochemicals, the production of total major chemicals and petrochemicals in India for April-September 2025 reached 27,322 thousand metric tonnes, indicating overall industry activity. While specific ethylene production figures from industrial associations for the immediate last year are not readily available, the capacity utilization for key petrochemical feedstocks, including ethylene, has experienced a declining trend since 2019, with a brief recovery in 2021-22, signifying potential vulnerabilities within the supply chain.
Key Market Drivers
Rising Downstream Demand and Packaging Growth Drive Ethylene Uptake
Growing demand from downstream industries significantly propels the India ethylene market, as ethylene serves as the primary feedstock for critical derivatives like polyethylene, essential for the rapidly expanding packaging, consumer goods, and infrastructure sectors. The burgeoning middle class and increasing urbanization in India directly translate to heightened consumption of packaged goods and durable plastics, escalating the demand for ethylene-based products. This growth is further amplified by the vibrant e-commerce sector, relying heavily on flexible and rigid packaging solutions. According to the Plastics Export Promotion Council, as reported in its "Analysis of India's Plastics Export" in September 2026, India's plastics and allied product exports posted 25.9% growth to USD 1327.4 million from the year-ago month, underscoring the substantial demand for polymer precursors. This expansion ensures a consistent and robust uptake of ethylene, driving both production and import requirements.
Domestic Capacity Expansion and Policy Support to Strengthen Petrochemical Supply
Another pivotal factor influencing the India ethylene market is the ongoing expansion of domestic petrochemical production capacity. Major industry players are strategically investing in new crackers and derivative units to cater to escalating domestic demand and reduce import reliance. This capacity expansion is often bolstered by government incentives fostering a self-reliant petrochemical sector. Indian Oil Corporation, according to Elite Wealth in October 2025, announced a capital expenditure of ₹33,494 crore for FY25–26 to drive refinery and petrochemical expansion. Such investments aim to enhance supply chain resilience and meet future consumption spikes. Overall, India is projected to see its chemical production increase by 10.9% in 2026, according to Indian Chemical News, driven by robust domestic demand and government support.
Download Free Sample Report
Key Market Challenges
Oil price volatility constrains India's ethylene growth
The volatility in crude oil prices presents a significant impediment to the growth of the India ethylene market. As naphtha, a primary feedstock for ethylene production, is a derivative of crude oil, fluctuations in global crude benchmarks directly translate into unpredictable and often elevated production costs for domestic manufacturers. This inherent instability in feedstock pricing compresses profit margins for producers, making long-term planning and investment in new capacity more challenging. For instance, according to the Chemicals & Petrochemicals Manufacturers' Association (CPMA) in a May 2026 report, while India's ethylene (C2) capacity is on track to exceed 9.5 million tonnes per year by 2027, the sector continuously navigates the impact of rising operational expenditures driven by such feedstock cost fluctuations.
Input-cost volatility raises derivative prices and dampens market expansion
This environment of fluctuating input costs discourages optimal capacity utilization and can lead to increased prices for ethylene derivatives, such as polyethylene, which in turn affects downstream industries like packaging and consumer goods. Consequently, the unpredictable cost structure driven by crude oil volatility constrains overall market expansion by dampening investor confidence and reducing the competitiveness of India's ethylene production.
Key Market Trends
Gas-Based Feedstock Shift and PDH-PP Investment at Usar
The increasing shift towards gas-based feedstocks represents a significant trend influencing the India ethylene market, primarily driven by the need to enhance cost stability and feedstock security. This transition away from naphtha, a crude oil derivative prone to price volatility, offers producers more predictable operational expenditures and reduces reliance on imported liquid feedstocks. Indian energy companies are strategically investing in infrastructure to facilitate this shift. For instance, according to fuzz - AI, August 2026, GAIL is progressing with its 500,000-tonne-a-year propane dehydrogenation-polypropylene project at Usar, described as India's first PDH-based polypropylene complex, entailing an estimated investment of approximately ₹11,256 crore. Such investments underline a strategic pivot to leverage domestically abundant or reliably imported gas resources, thereby fostering a more resilient petrochemical sector.
Regulatory Push for Recycled Content in Ethylene Derivatives
Another key trend is the accelerating growth in sustainable and recyclable ethylene derivatives, propelled by evolving environmental regulations and increasing consumer demand for eco-friendly products. This trend mandates that manufacturers innovate in polymer design and production processes to create materials with improved recyclability or higher recycled content. Regulatory frameworks are playing a crucial role in shaping this shift. According to Packaging Insights, April 2026, in its article 'India tightens plastic waste rules to boost recycling and reuse', India's Plastic Waste Management (Amendment) Rules mandate that for Category I rigid packaging, the required recycled content is set to increase from 30% in 2025-2026 to 40% in 2026-2027. This regulatory push creates a consistent demand signal for recycled polymers, driving investments in recycling infrastructure and the development of new, circular-economy-aligned ethylene derivatives.
Segmental Insights
Polyethylene: Fastest-Growing Segment Fueled by Packaging, Infrastructure, and Domestic Manufacturing Initiatives
In the India Ethylene Market, Polyethylene stands out as the fastest-growing segment, primarily driven by its extensive and diverse applications across key industrial sectors. This rapid expansion is underpinned by the increasing demand from the burgeoning packaging industry, fueled by urbanization, evolving consumer habits, and the robust growth of e-commerce platforms requiring flexible and rigid packaging solutions. Furthermore, significant infrastructure development initiatives and the expanding automotive sector in India, which relies on polyethylene for lightweight and durable components, consistently contribute to the heightened demand for this versatile polymer. The government's "Make in India" campaign also supports domestic manufacturing, indirectly bolstering the need for polyethylene as a fundamental raw material.
Regional Insights
Western Region Leads India's Ethylene Market
The Western region of India holds a dominant position in the India Ethylene Market, primarily driven by its robust industrial infrastructure and established petrochemical clusters. States like Gujarat and Maharashtra are home to several significant industrial hubs with substantial investments in the petrochemical and chemical industries, which are heavy consumers of ethylene. This region benefits from its strategic proximity to major ports, facilitating efficient import of feedstock and export of ethylene-based products. Furthermore, the presence of major oil refineries ensures a stable supply of crucial feedstocks like naphtha and natural gas, supporting large and advanced petrochemical complexes. This combination of infrastructure, feedstock availability, and logistical advantages solidifies the West's leadership in the market.
Recent Developments
-
In May 2025, GAIL (India) Limited revealed its capital expenditure plan for the financial year 2025-26, allocating ₹10,700 crore for capacity expansion across all its verticals. Notably, the company proposed an increased investment of ₹3,000 crore, representing 28% of the total capital expenditure, specifically for the petrochemical sector. This substantial financial commitment underscores GAIL's focus on enhancing its petrochemical portfolio, including projects related to ethylene and its derivatives, to address the escalating domestic demand, thereby reinforcing growth within the India ethylene market.
-
In August 2024, Indian Oil Corporation Limited (IOCL) outlined its strategic plan to significantly expand its petrochemical operations. The company aimed to triple its overall petrochemical capacity by 2030, starting from 4.28 million tonnes per year. This expansion strategy includes substantial additions to its ethylene capacity, which is a core component of its petrochemical business. As of 2025, IOCL held a considerable share of India's ethylene capacity, and these planned additions were designed to further strengthen its position and meet the growing domestic demand for ethylene-based products within the India ethylene market.
-
In July 2024, Hindustan Petroleum Corporation Limited (HPCL) announced the commencement of several new projects focused on ethylene derivatives. The company proposed two separate initiatives for the production of Linear Low Density Polyethylene (LLDPE) and High Density Polyethylene (HDPE), each with an annual capacity of 550,000 tonnes. Additionally, HPCL initiated a 1 million tonnes per annum polypropylene (PP) project. These new product launches and expansions directly impact the India ethylene market by increasing the demand for ethylene as a primary feedstock for these polymer productions.
-
In June 2024, GAIL (India) Limited announced a significant investment of ₹60,000 crore for establishing a 1.5 million tonnes per annum (mtpa) ethane cracker project in Ashta, Sehore district, Madhya Pradesh. This ambitious undertaking aims to produce various ethylene derivatives, directly contributing to the expansion of India's ethylene production capacity. The project involves converting ethane, a natural gas component, into ethylene, a fundamental chemical for plastics and other petrochemicals. Groundbreaking for this crucial project is anticipated by February 2025, with commercial production slated to commence by the financial year 2030-31, bolstering the India ethylene market significantly.
Key Market Players
- Reliance Industries Ltd
- Indian Oil Corporation Ltd
- Haldia Petrochemicals Ltd
- GAIL India Ltd
- Bharat Petroleum Corporation Ltd
- Oil and Natural Gas Corporation Ltd
- Nayara Energy Ltd
- Mangalore Refinery and Petrochemicals Ltd
- Chennai Petroleum Corporation Ltd
- Shell India Markets Pvt Ltd
|
By Feedstock
|
By Application
|
By Region
|
- Naphtha
- Ethane
- Propane
- Butane
|
- Polyethylene
- Ethylene Oxide
- Ethyl Benzene
- Ethylene Dichloride
|
- North India
- East India
- West India
- South India
|
Report Scope:
In this report, the India Ethylene Market has been segmented into the following categories, in addition to the industry trends which have also been detailed below:
-
India Ethylene Market, By Feedstock:
-
Naphtha
-
Ethane
-
Propane
-
Butane
-
India Ethylene Market, By Application:
-
Polyethylene
-
Ethylene Oxide
-
Ethyl Benzene
-
Ethylene Dichloride
-
India Ethylene Market, By Region:
-
North India
-
East India
-
West India
-
South India
Competitive Landscape
Company Profiles: Detailed analysis of the major companies present in the India Ethylene Market.
Available Customizations:
India Ethylene Market report with the given market data, TechSci Research offers customizations according to a company's specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to five).
India Ethylene Market is an upcoming report to be released soon. If you wish an early delivery of this report or want to confirm the date of release, please contact us at sales@techsciresearch.com