|
Key Insights
|
Details
|
|
Forecast Period
|
2027-2032
|
|
Market Size (2025)
|
USD 950.43 Million
|
|
CAGR (2026-2031)
|
7.41%
|
|
Fastest Growing Segment
|
Plasticizers
|
|
Largest Market
|
West
|
|
Market Size (2031)
|
USD 1459.45 Million
|
Market Overview
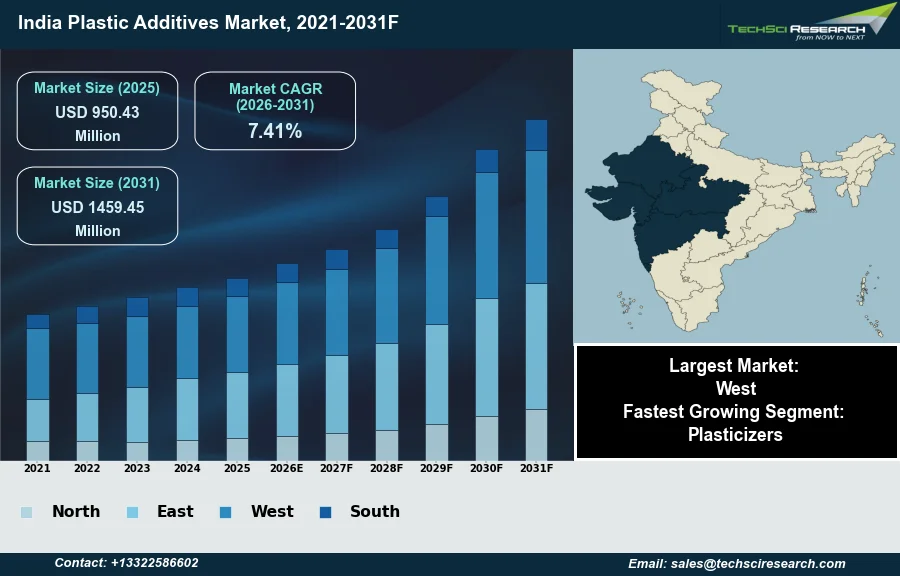
The India Plastic Additives Market is expected to grow from USD 950.43 Million in 2025 to USD 1459.45 Million by 2031 at a 7.41% CAGR. Plastic additives are chemical substances integrated into polymers during manufacturing to enhance or modify their properties, optimizing performance, appearance, and durability for a vast array of industrial applications. The India Plastic Additives Market is primarily driven by robust domestic demand from sectors such as packaging, infrastructure, healthcare, and consumer goods, underpinned by increasing urbanization and disposable incomes. This growth is further supported by government initiatives promoting manufacturing and infrastructure development. According to the Plastics Export Promotion Council (PLEXCONCIL), India's plastics exports, indicative of overall sector vitality, achieved US$ 12.5 billion in the financial year 2024-25, marking an 8% increase.
However, a significant challenge impeding market expansion stems from escalating environmental and regulatory compliance pressures, particularly the stringent implementation of plastic waste management rules and Extended Producer Responsibility (EPR) obligations. The existing underdeveloped recycling infrastructure and the operational and financial burden of adherence for manufacturers, particularly small and medium-sized enterprises, pose considerable hurdles to sustained growth.
Key Market Drivers
End-use Industry Expansion Drives Indian Plastic Additives Demand
Expanding end-use industries represent a primary driver for the India Plastic Additives Market, as robust growth in sectors such as automotive, construction, and packaging directly translates into increased demand for plastics and their modifying additives. The rapid expansion of these manufacturing segments necessitates plastic materials that can meet diverse application requirements. For instance, the Indian automotive sector's production figures highlight this expansion; according to the Press Information Bureau, February 2026, citing the Society of Indian Automobile Manufacturers (SIAM), passenger vehicle production in India reached 4.902 million units in FY 2023-24. This sustained output directly fuels the consumption of plastic additives like impact modifiers and heat stabilizers for various automotive parts.
Rising Performance Demands and Recyclability Drive Additive Adoption
The escalating demand for enhanced plastic performance and durability significantly influences the market. As industries require plastics with superior characteristics, such as improved mechanical strength, UV resistance, flame retardancy, and sustainable attributes like recyclability, the integration of specialized additives becomes essential. This trend is evident in the packaging sector's push for more environmentally sound solutions; according to The CSR Universe, July 2024, in the 'Colgate-Palmolive India Transitions 50% of Toothpaste Portfolio to Recyclable Tubes...' report, Colgate-Palmolive (India) Ltd transitioned 50% of its toothpaste portfolio to recyclable tubes by volume in FY 2023-24, aiming for 100% recyclability by FY 2024-25. Such initiatives necessitate performance additives that enable recyclability. The broader chemical and petrochemical sector also demonstrates considerable activity; according to the Department of Chemicals and Petrochemicals, in 2024-25 (April-September 2024), the production of major chemicals and petrochemicals reached 28,292 thousand metric tons.
Download Free Sample Report
Key Market Challenges
Regulatory Push for Recycled Content and Associated Costs
Escalating environmental and regulatory compliance pressures, coupled with an underdeveloped recycling infrastructure, represent a significant impediment to the growth of the India Plastic Additives Market. The stringent implementation of plastic waste management rules and Extended Producer Responsibility (EPR) obligations directly impacts plastic manufacturers by imposing substantial operational and financial burdens. These regulations mandate increasing recycled content in plastic packaging. For instance, rigid plastics require 30% recycled content in financial year 2025–26, with flexible plastics needing 10% and multilayered plastics 5%. Such requirements necessitate significant investment in new formulations and processing technologies to ensure the quality and performance of recycled materials, posing a financial strain on producers.
Infrastructure Gaps and Feedstock Scarcity Hindering Growth
The existing underdeveloped recycling infrastructure further exacerbates these challenges, as manufacturers struggle to source consistent, high-quality recycled feedstocks and meet ambitious targets. This drives up operational costs and limits production flexibility across the plastics industry. According to a July 2025 NITI Aayog report, a key challenge for plastic additives, including flame retardants, is the limited investment in manufacturing high-performance additives and restricted access to low-cost raw materials. This scarcity and the financial strain on the broader plastics industry ultimately slow down the demand for specialized plastic additives and hinder overall market expansion.
Key Market Trends
Sustainable Additives Gain Momentum in India
Growing adoption of sustainable and eco-friendly additives represents a significant trend, driven by heightened environmental consciousness and evolving regulatory landscapes, compelling manufacturers to integrate additives that diminish the environmental impact of plastics. This encompasses bio-based additives from renewable resources, biodegradable solutions, and those enhancing recyclability and circularity of plastic materials. The India Plastic Additives Market is experiencing a decisive shift towards these formulations as companies strive to fulfill Extended Producer Responsibility obligations and cater to consumer demand for greener products. These additives are vital for improving the performance and processability of recycled plastics, enabling their broader industrial application. For instance, the Uttar Pradesh Bio-plastic Industry Policy, 2024, provides incentives to attract a Rs 1,000 crore anchor polylactic acid unit.
3D Printing Fuels Demand for Custom Additives
The burgeoning field of additive manufacturing, or 3D printing, significantly influences the India Plastic Additives Market by generating demand for highly specialized materials. These technologies necessitate plastics with precise properties such as enhanced flow characteristics, superior mechanical strength, thermal stability, and UV resistance, achievable through advanced additive incorporation. As industrial applications of 3D printing expand across sectors like automotive prototyping, medical devices, and consumer goods, the requirement for tailor-made additive formulations intensifies, driving innovation and investment. This creates new avenues for additive manufacturers to develop customized solutions for complex designs and high-performance needs. As of 2023, India's 3D printing market was valued at approximately USD 61.4 million, reflecting this growing industrial adoption.
Segmental Insights
Growth Drivers: PVC Demand, Infrastructure Expansion, and the Regulatory Shift toward Eco-Friendly Plasticizers
The Plasticizers segment is experiencing rapid growth within the India Plastic Additives Market, emerging as a key driver for market expansion. This accelerated growth is primarily attributed to the burgeoning demand for flexible polyvinyl chloride (PVC) products across vital end-use industries, including packaging, automotive, and construction. Significant government initiatives promoting urbanization and infrastructure development further amplify the need for plasticizers in applications such as wiring, flooring, and pipes. Concurrently, stringent regulatory frameworks from bodies like the Bureau of Indian Standards and the Ministry of Environment, Forest, and Climate Change, which emphasize limiting hazardous chemicals and promoting sustainable alternatives, compel a shift towards eco-friendly and non-phthalate plasticizers.
Regional Insights
Western Region Dominates India Plastic Additives Market Through Industrial Clusters, Port Access, and End-Use Demand.
The Western region unequivocally leads the India Plastic Additives Market, a position solidified by its established industrial ecosystem. This dominance is primarily driven by the presence of dense petrochemical clusters and integrated manufacturing facilities across Gujarat and Maharashtra, which ensure a robust supply chain from feedstock to polymer production. Crucially, the region's strategic access to major ports like Nhava Sheva and Pipavav facilitates efficient logistics for both raw material procurement and finished product distribution, including exports. Additionally, a concentrated base of key end-use industries, such as packaging, automotive, and construction, drives significant demand for plastic additives, further entrenching the West's leading market share.
Recent Developments
-
In October 2025, Bhageria Industries Limited, an Indian specialty chemicals manufacturer, commenced commercial production of a new line of plasticizers and ethoxylates. This product launch, enabled by regulatory approval, introduced plasticizers designed to enhance the flexibility and durability of PVC, which are critical properties for various applications including cables, flooring, footwear, and automotive components. The company indicated its intention to supply both domestic and international markets, addressing the increasing demand within polymer-based value chains.
-
In July 2024, Lubrizol announced an investment of $200 million for a new additive manufacturing facility in Aurangabad, India. This strategic expansion followed the signing of a Memorandum of Understanding and aimed to significantly boost the company's production capacity for various additives. The facility was intended to cater to the growing demand for specialized chemical additives within the Indian market, as well as for export, highlighting the region's expanding industrial footprint.
-
In July 2024, Evonik reported a strong performance in its second quarter, surpassing analyst expectations, and subsequently raised its full-year adjusted EBITDA outlook. This positive financial outcome was partly attributed to favorable volume development within its Specialty Additives business. The company maintained stringent cost controls, which, combined with a recovery in animal nutrition pricing and reduced production expenses, contributed to robust operational results in a challenging economic climate.
-
In April 2024, BASF showcased its sustainable additive solutions at CHINAPLAS 2024, emphasizing their role in advancing the circular economy for plastics. The company presented IrgaCycle, an additive solution developed to improve the mechanical recycling process and enhance the performance of recycled plastics. Additionally, BASF introduced its first biomass balance plastic additives, Irganox® 1010 BMBcert™ and Irganox® 1076 FD BMBcert™, which are certified for mass balance and support the use of renewable feedstock in plastic production.
Key Market Players
- BASF India Limited
- Dow
- Evonik
- Clariant
- Songwon
- LANXESS
- Baerlocher
- Valtris
- Adeka
- Akdeniz Kimya
|
By Type
|
By Application
|
By Region
|
- Plasticizers
- Stabilizers
- Flame Retardant’s
- Impact Modifiers
|
- Packaging
- Automotive
- Construction
- Electrical
- Others
|
- North India
- East India
- West India
- South India
|
Report Scope:
In this report, the India Plastic Additives Market has been segmented into the following categories, in addition to the industry trends which have also been detailed below:
-
India Plastic Additives Market, By Type:
-
Plasticizers
-
Stabilizers
-
Flame Retardant’s
-
Impact Modifiers
-
India Plastic Additives Market, By Application:
-
Packaging
-
Automotive
-
Construction
-
Electrical
-
Others
-
India Plastic Additives Market, By Region:
-
North India
-
East India
-
West India
-
South India
Competitive Landscape
Company Profiles: Detailed analysis of the major companies present in the India Plastic Additives Market.
Available Customizations:
India Plastic Additives Market report with the given market data, TechSci Research offers customizations according to a company's specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to five).
India Plastic Additives Market is an upcoming report to be released soon. If you wish an early delivery of this report or want to confirm the date of release, please contact us at sales@techsciresearch.com