|
Key Insights
|
Details
|
|
Forecast Period
|
2027-2031
|
|
Market Size (2025)
|
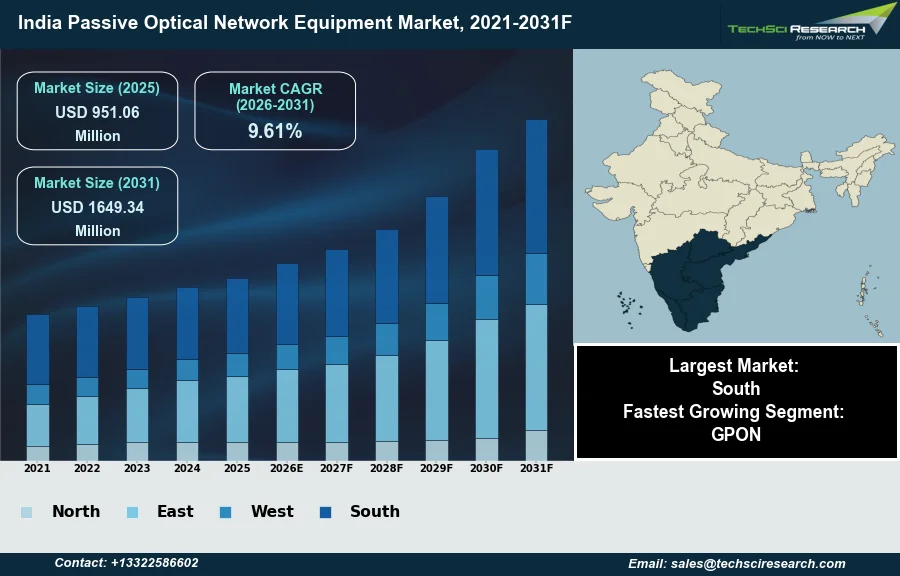
USD 951.06 Million
|
|
CAGR (2026-2031)
|
9.61%
|
|
Fastest Growing Segment
|
GPON
|
|
Largest Market
|
South
|
|
Market Size (2031)
|
USD 1649.34 Million
|
Market Overview
The India Passive Optical Network Equipment Market is expected to grow from USD 951.06 Million in 2025 to USD 1649.34 Million by 2031 at a 9.61% CAGR. Passive Optical Network (PON) equipment comprises infrastructure components, such as Optical Line Terminals (OLTs) and Optical Network Units (ONUs) or Optical Network Terminals (ONTs), essential for delivering high-speed broadband services via fiber-to-the-x (FTTx) deployments over optical fiber. The market's expansion is primarily driven by the rising demand for high-bandwidth applications, the growing adoption of Fiber-to-the-Home (FTTH) services, and government initiatives aimed at digital inclusion and improved broadband access across urban and rural areas. These factors collectively necessitate a robust last-mile fiber infrastructure, thereby increasing the demand for PON solutions.
A notable challenge to market growth is the significant initial capital expenditure required for deploying optical fiber networks and associated PON infrastructure, particularly within India's geographically diverse and remote regions. Despite this, the market continues to exhibit growth. According to the Telecom Regulatory Authority of India (TRAI), during the fiscal year 2025-26, India added 11.21 million new wireline connections.
Key Market Drivers
FTTH Adoption Drives PON Equipment Demand in India
Increased Fiber-to-the-Home (FTTH) adoption stands as a pivotal driver for the India Passive Optical Network Equipment Market. As internet consumption surges and demand for high-speed, reliable broadband intensifies across residential and commercial sectors, service providers are compelled to expand their fiber infrastructure directly to end-user premises. This expansion directly translates into a heightened requirement for PON components such as Optical Line Terminals and Optical Network Units. The robust demand for faster internet connections, especially for streaming, online gaming, and remote work, fuels FTTH deployments. According to Bharti Airtel's Q4 FY26 earnings report, released in May 2026, the company added approximately 1.1 million new home customers during the quarter.
5G Rollout and Fiberization Fuel PON Market Growth
The extensive 5G rollout and associated network fiberization initiatives are also significantly propelling the PON equipment market in India. Achieving the full potential of 5G networks, characterized by ultra-low latency and high bandwidth, necessitates a dense and robust fiber backhaul infrastructure to connect numerous small cells and base stations. This requirement for fiberization across fronthaul, midhaul, and backhaul segments directly boosts the demand for PON solutions, which are instrumental in efficiently managing last-mile fiber connectivity to 5G network elements. As per a statement by the Ministry of Communications, in July 2026, the number of 5G Base Transceiver Stations (BTSs) across India had increased to 562,971 as of June 30, 2026. This strategic push is also contributing to the overall growth in fixed-line connectivity. According to the Telecom Regulatory Authority of India, in its report for September 2026, the total wireline subscriber base in the country reached 48.74 million.
Download Free Sample Report
Key Market Challenges
Capital-Expenditure Constraints Limit PON Deployment
The significant initial capital expenditure required for deploying optical fiber networks and associated Passive Optical Network (PON) infrastructure presents a notable challenge to market expansion. This substantial upfront investment, particularly across India's geographically diverse and often remote regions, directly limits the pace and scale of network rollout. Companies face considerable financial hurdles in laying extensive fiber optic cables and establishing the necessary OLTs and ONUs, impacting their ability to connect underserved areas. This cost burden can deter new entrants and slow down incumbent operators' expansion plans, thus restricting the overall growth of the PON equipment market.
Capex Gap and ROI Uncertainty Impede Fiber Investment
The capital-intensive nature of fiber infrastructure deployment necessitates large-scale funding and a clear, long-term return on investment strategy, which can be challenging to ascertain in less densely populated or economically viable regions. According to the Cellular Operators Association of India (COAI), in its Annual Report 2025-26, the sector faced a capital expenditure revenue gap exceeding ₹10,000 crore. This substantial financial gap highlights the ongoing strain on infrastructure providers, directly impeding their capacity for continued investment in network upgrades and expansion necessary for the India Passive Optical Network Equipment Market to realize its full potential.
Key Market Trends
Adoption of next-generation PON and equipment upgrades
The adoption of next-generation Passive Optical Network (PON) technologies, including XGS-PON and 50G PON, is a significant trend as service providers anticipate escalating bandwidth demands. These technologies offer substantially higher symmetrical speeds than legacy GPON, crucial for supporting data-intensive applications, cloud services, and emerging high-bandwidth needs across India. This necessitates infrastructure upgrades, particularly for Optical Line Terminals and Optical Network Units, driving demand for advanced PON equipment. According to a Press Information Bureau report, July 23, 2026, in "Steps taken to strengthen Telecommunication and Digital Communication Infrastructure", 136 R&D projects with sanctioned funding of nearly ₹543 crores, covering optical systems, had been approved under the Telecom Technology Development Fund scheme as of June 30, 2026.
Expanded fiber penetration into Tier 2/3 and rural India driving PON deployment
Deepening fiber penetration into India's Tier 2, Tier 3 cities, and rural areas represents another pivotal market trend, expanding beyond urban centers for comprehensive digital inclusion. This geographical rollout is largely driven by government initiatives for universal broadband access and growing demand from underserved populations for high-speed internet. Such widespread deployment requires extensive PON infrastructure, from central office OLTs to numerous ONUs and ONTs, creating new growth opportunities for equipment manufacturers. According to a TelecomLead report, October 27, 2026, in "Top 10 Countries Investing in Fiber Broadband in 2026", nearly 7 lakh kilometers of optical fiber cable had already been laid under India's amended BharatNet program, aiming to connect approximately 6.5 lakh villages.
Segmental Insights
GPON Leads India's PON Market Growth Driven by Demand, Government Initiatives, and Technical Advantages
The India Passive Optical Network Equipment Market is experiencing significant expansion, with the Gigabit Passive Optical Network (GPON) segment emerging as the fastest-growing. This rapid growth is primarily driven by the escalating demand for high-speed internet connectivity across urban and semi-urban areas. Government initiatives, such as the BharatNet program and Smart Cities Mission, are actively promoting widespread broadband penetration and the development of robust digital infrastructure, which in turn fuels GPON adoption. Furthermore, GPON's inherent advantages, including superior bandwidth capacity, cost-effectiveness, and reliability over traditional copper networks, position it as a preferred technology for delivering advanced triple-play services and supporting the rollout of 5G infrastructure. Regulatory bodies like the Department of Telecommunications (DoT) also support this expansion through various policy frameworks.
Regional Insights
South India Drives PON Growth via Digital Maturity
The South region is a key driver in the India Passive Optical Network Equipment Market, largely due to its advanced digital ecosystem and consistent technological adoption. The presence of prominent information technology hubs, such as Bengaluru, Hyderabad, and Chennai, fuels substantial demand for high-speed, reliable broadband infrastructure to support extensive commercial operations and data centers. Furthermore, the region benefits from higher digital literacy rates and a tech-savvy populace, leading to a greater embrace of fiber-to-the-home (FTTH) services and other advanced digital applications. Significant investment in urban infrastructure and proactive integration of digital connectivity initiatives further consolidates South India’s market leadership in passive optical network deployments.
Recent Developments
-
In August 2025, Alphion India Private Limited successfully implemented XGS-PON (10 Gigabit Symmetrical Passive Optical Network) technology at the Indian Institute of Technology (IIT) Delhi. This made IIT Delhi the first campus in India to adopt this advanced fiber access solution, significantly enhancing its digital capabilities. The implementation provided high-speed, symmetrical upstream and downstream connectivity, optimizing network efficiency and user experience. Alphion India’s tailored solution seamlessly integrated with the institute's existing GPON infrastructure, ensuring continuity while upgrading to next-generation speeds, showcasing a breakthrough in enterprise passive optical networking in India.
-
In March 2025, HFCL Limited completed a significant expansion of its optical fiber and optical fiber cable manufacturing capacity. The company expanded its optical fiber capacity from 12 million fkm to 33 million fkm and its high-quality optical fiber cable capacity from 25 million fkm to 35 million fkm. This strategic investment was aimed at meeting the increasing demand for optical fiber cables, which are essential components for Passive Optical Network deployments in India and global markets. The expansion bolstered HFCL's ability to support India's digitization initiatives, including the BharatNet program and the rollout of 4G and 5G networks.
-
In December 2024, Tejas Networks announced it was selected to supply its Gigabit Passive Optical Network (GPON) optical line terminal (OLT), optical network terminal (ONT), and management system for the BharatNet Last Mile Connectivity (LMC) project in Tamil Nadu. This significant collaboration involved Tamil Nadu FibreNet Corporation Limited (TANFINET) and aimed to extend affordable, high-speed connectivity to approximately 50,000 government institutions, public health centers, and schools. The project also sought to leverage this infrastructure to provide fiber-to-the-home (FTTH) services to rural households in Tamil Nadu, marking a crucial step in India's digital inclusion efforts with indigenous PON equipment.
-
In November 2024, ITI Limited, in collaboration with a consortium partner, was declared the lowest bidder for two significant packages under BharatNet Phase III. These contracts, valued at ₹30.22 billion, focused on the design, supply, construction, installation, upgrade, operation, and maintenance of the middle-mile network in Himachal Pradesh, West Bengal, and the Andaman & Nicobar Islands. As a manufacturer of Gigabit Passive Optical Network systems, ITI Limited's involvement as a key player in this national broadband initiative underscored its strategic role in expanding India's optical fiber infrastructure and passive optical network equipment deployment.
Key Market Players
- Sterlite Technologies Ltd
- Reliance Jio
- Bharti Airtel
- Finolex Cables Ltd
- Corning
- CommScope
- Fujikura
- TE Connectivity
- Accelink
- Sumitomo Electric
|
By Component
|
By Type
|
By Application
|
By End User
|
By Region
|
- Wavelength Division Multiplexer/De-Multiplexer
- Optical filters
- Optical power splitters
- Optical cables
- Optical Line Terminal (OLT)
- Optical Network Terminals (ONT)
- Others
|
- Gigabit Passive Optical Network (GPON)
- Ethernet Passive Optical Network (EPON)
- Next Generation Passive Optical Network (NG PON)
- Others
|
- FTTH (Fiber to the Home)
- FTTx (Fiber to the X)
- Mobile Backhaul
|
- Residential
- Commercial
- Industrial
|
- North India
- East India
- West India
- South India
|
Report Scope:
In this report, the India Passive Optical Network Equipment Market has been segmented into the following categories, in addition to the industry trends which have also been detailed below:
-
India Passive Optical Network Equipment Market, By Component:
-
Wavelength Division Multiplexer/De-Multiplexer
-
Optical filters
-
Optical power splitters
-
Optical cables
-
Optical Line Terminal (OLT)
-
Optical Network Terminals (ONT)
-
Others
-
India Passive Optical Network Equipment Market, By Type:
-
Gigabit Passive Optical Network (GPON)
-
Ethernet Passive Optical Network (EPON)
-
Next Generation Passive Optical Network (NG PON)
-
Others
-
India Passive Optical Network Equipment Market, By Application:
-
FTTH (Fiber to the Home)
-
FTTx (Fiber to the X)
-
Mobile Backhaul
-
India Passive Optical Network Equipment Market, By End User:
-
Residential
-
Commercial
-
Industrial
-
India Passive Optical Network Equipment Market, By Region:
-
North India
-
East India
-
West India
-
South India
Competitive Landscape
Company Profiles: Detailed analysis of the major companies present in the India Passive Optical Network Equipment Market.
Available Customizations:
India Passive Optical Network Equipment Market report with the given market data, TechSci Research offers customizations according to a company's specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to five).
India Passive Optical Network Equipment Market is an upcoming report to be released soon. If you wish an early delivery of this report or want to confirm the date of release, please contact us at sales@techsciresearch.com