|
Key Insights
|
Details
|
|
Forecast Period
|
2027-2031
|
|
Market Size (2025)
|
USD 10.45 Billion
|
|
CAGR (2026-2031)
|
9.78%
|
|
Fastest Growing Segment
|
Online
|
|
Largest Market
|
North
|
|
Market Size (2031)
|
USD 18.29 Billion
|
Market Overview
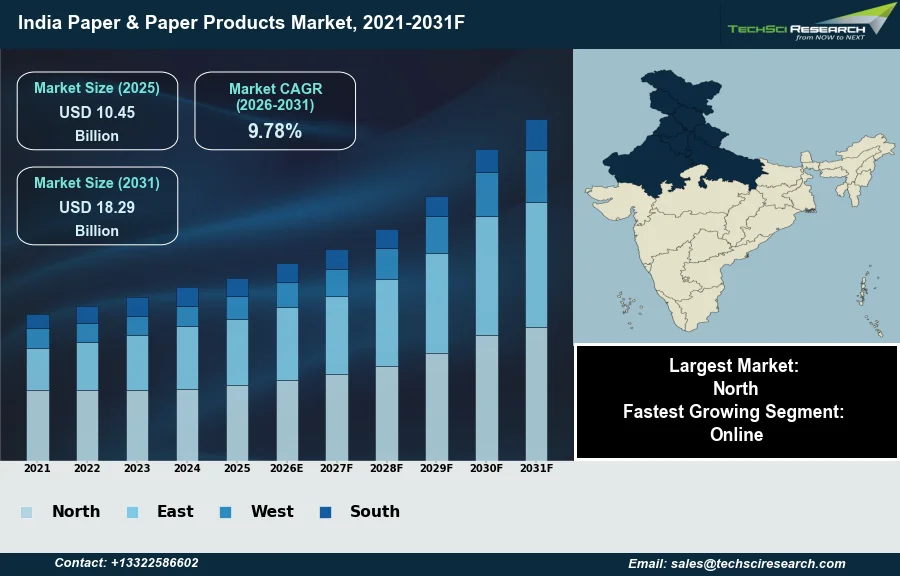
The India Paper & Paper Products Market is expected to grow from USD 10.45 Billion in 2025 to USD 18.29 Billion by 2031 at a 9.78% CAGR. The India Paper & Paper Products market encompasses diverse materials such as printing and writing paper, packaging boards, and specialty papers, essential for various sectors including education, communication, packaging, and hygiene. Growth in this market is primarily driven by India's expanding literacy rates, the robust e-commerce sector, and increasing urbanization, contributing to higher demand for packaged goods and disposable paper products. According to the Indian Paper Manufacturers Association, in 2025-26, the country's paper industry recorded an annual production of approximately 25 million tonnes across its operational mills.
These fundamental economic and demographic shifts underpin consistent market expansion, distinct from short-term market trends. However, a significant impediment to sustained market growth is the escalating volume of paper and paperboard imports. According to data released by the Department of Commerce, Government of India, and cited by the Indian Paper Manufacturers Association, imports reached a record 2.05 million tonnes in FY25, representing a substantial increase over prior years. This surge, particularly from certain Asian economies, strains domestic manufacturing capacities and impacts profitability across the industry.
Key Market Drivers
E-commerce Growth Drives Packaging Demand
The substantial expansion of the e-commerce sector significantly fuels demand within the India Paper & Paper Products market. As online retail continues its rapid growth across the country, the need for robust and efficient packaging solutions, primarily corrugated boxes and other paper-based materials, escalates. These solutions are crucial for ensuring product safety during transit and meeting increasing consumer expectations for secure deliveries. This surge directly translates into higher consumption of packaging paper and paperboard. According to Univest, in August 2026, the e-commerce packaging market in India is valued at approximately ₹25,000 crore, underscoring its pivotal role as a market driver.
Regulatory Push and Sustainability Drive Paper Packaging Adoption
Concurrently, stringent plastic ban regulations and the strong push for sustainable alternatives are reshaping the industry landscape. With government mandates restricting single-use plastics and growing consumer preference for eco-friendly options, businesses are increasingly transitioning to paper-based packaging across various sectors, including fast-moving consumer goods and food services. This shift directly stimulates demand for innovative and recyclable paper products. According to an October 2026 news article from the Indian Paper Manufacturers Association (IPMA), around 76% of India's paper output in 2024-25 was based on recovered paper and recycled fiber, highlighting the industry's commitment to sustainability. Further demonstrating market confidence and expansion, according to Projects India, in October 2026, 187 upcoming paper and paper products projects are being tracked across India, with a combined recorded cost of approximately Rs 1.37 lakh crore.
Download Free Sample Report
Key Market Challenges
Imports Surge Strains Domestic Capacity and Profitability
The escalating volume of paper and paperboard imports presents a significant challenge to the India Paper & Paper Products market. This influx of foreign products directly strains domestic manufacturing capacities, leading to underutilization of local production facilities and intense price competition. The increased market presence of imports impacts the profitability of Indian paper manufacturers, as they contend with lower-priced alternatives, particularly from certain Asian economies.
Import Pressure Undermines Growth and Investment
This competitive pressure directly hampers sustained market growth by eroding the financial viability of domestic operations and discouraging fresh investments in modernization and expansion. When local manufacturers face reduced margins due to cheaper imports, their ability to allocate capital for technological upgrades or capacity enhancements diminishes. According to the India Brand Equity Foundation, during Financial Year 2026, imports of paper, paperboard, and newsprint reached 2,552.8 thousand tonnes. This consistent increase in import volumes curtails the potential for indigenous growth and development within the Indian paper sector.
Key Market Trends
Premium Packaging Upgrades and Barrier Coatings
The India Paper & Paper Products market is significantly influenced by the premiumization and functional enhancements in paper packaging. This trend moves beyond basic containment to incorporate advanced features that improve product protection, shelf appeal, and consumer convenience, driven by evolving industry requirements for high-performance materials. These enhancements include specialized barrier coatings to protect against moisture, grease, and oxygen, crucial for food and pharmaceutical applications. According to The Pulp and Paper Times, in June 2025, the barrier paper market in India is projected to unlock a $4 billion market by 2030, marking a significant leap in sustainable packaging.
Growth of Paper Hygiene Segment
Concurrently, the growing consumption of paper-based hygiene products represents another pivotal trend reshaping the market. Increased health consciousness, rising disposable incomes, and rapid urbanization are driving demand for various hygiene products such as facial tissues, toilet paper, and kitchen towels. This shift reflects a broader consumer preference for convenience and improved sanitation standards across both household and institutional settings. According to The Pulp and Paper Times in August 2026, the tissue and hygiene segment in India is growing at an estimated 11–13% annually.
Segmental Insights
Online E-commerce Spurs Growth in Sustainable Paper Packaging
The India Paper & Paper Products Market is experiencing significant transformation, with the Online segment emerging as the fastest-growing due to robust e-commerce expansion. This rapid acceleration is primarily driven by the exponential rise in online shopping, fueled by increasing internet penetration and widespread smartphone adoption across the nation. Consequently, there is an unprecedented demand for reliable and sustainable paper-based packaging solutions, such as corrugated boxes and paperboard, essential for the secure delivery of products across diverse online retail categories, including fast-moving consumer goods, electronics, and pharmaceuticals. Furthermore, heightened environmental awareness among consumers and governmental thrusts towards eco-friendly alternatives, including regulations against single-use plastics, have significantly boosted the preference for recyclable paper packaging in the online supply chain. This trend is also supported by initiatives from the Department for Promotion of Industry and Internal Trade (DPIIT) that foster digital trade.
Regional Insights
North Region's Market Leadership Fueled by Agro-Residues and Mill Concentration
The North region holds a leading position in the India Paper & Paper Products Market, primarily driven by the significant availability of agro-residues. States within North India, particularly Uttar Pradesh, benefit from abundant sugarcane cultivation, providing a consistent and cost-effective source of bagasse, a crucial raw material for paper manufacturing. This consistent raw material supply has fostered a high concentration of paper mills across the region, including notable facilities such as Khanna Paper Mills in Punjab, Century Pulp and Paper in Uttarakhand, and Accurate Paper Mills in Uttar Pradesh. The robust presence of these manufacturing units, further supported by active industry representation from organizations like the Northern India Paper Mill Association, underpins North India's market dominance through a strong production base and efficient catering to regional demand.
Recent Developments
-
In September 2025, ITC Paperboards & Specialty Papers Division (PSPD) highlighted its commitment to sustainability through significant research and development efforts. The company leveraged its R&D capabilities to launch various paper-based alternatives to single-use plastics, addressing critical environmental concerns in the Indian packaging segment. Notably, the 'Filo' series of sustainable paperboards gained considerable traction, both domestically and internationally. These innovations, designed to offer sustainable packaging solutions and lightweight options for customers, underscored ITC PSPD's role in driving eco-friendly advancements and fulfilling the growing demand for sustainable materials in India's paper and packaging market.
-
In February 2025, Emami Paper Mills focused on expanding its product portfolio within the Indian paper industry by introducing specialized items. The company successfully launched Oil and Grease Resistant (OGR) paper and Bulky paper. These new products were developed as part of Emami Paper Mills' strategy to build a future-ready product range, driven by continuous investments in technology and a consumer-centric approach to product development. The introduction of these specialized papers aimed to cater to evolving market demands and reinforce the company's position through innovation in India's competitive paper sector.
-
In October 2024, ITC's Packaging & Printing Business announced a significant collaboration with British sustainable packaging company Frugalpac to introduce paper Frugal Bottles in India and South Asia. This initiative aimed to decarbonize the drinks industry by promoting and eventually producing these low-carbon bottles locally. The Frugal Bottle, crafted from 94% recycled paperboard with a food-grade pouch, was noted for being substantially lighter than glass bottles and having a significantly reduced carbon and water footprint. This partnership underscored ITC's Sustainability 2.0 plan, focusing on climate change mitigation and fostering a circular economy for packaging waste within the Indian market.
-
In May 2024, Andhra Paper Limited signed an agreement with Valmet AB for the supply and commissioning of a new tissue paper production line at its Kadiyam facility, representing a capital expenditure of approximately INR 125 crores. This strategic investment aimed to diversify the company's product portfolio with a daily production capacity of 129 tons of various tissue paper grades. Subsequently, in August 2025, the company announced a further capital expenditure of ₹178 crore to upgrade its Paper Machine-3 (PM-3) at the Rajahmundry unit, projected to increase its capacity by 60 tonnes per day. These initiatives demonstrated Andhra Paper Limited's commitment to enhancing production capabilities and meeting the rising demand for high-quality paper products in the Indian market.
Key Market Players
- JK Paper Ltd
- West Coast Paper Mills Ltd
- Tamil Nadu Newsprint and Papers Ltd
- Ballarpur Industries Ltd
- Seshasayee Paper and Boards Ltd
- Century Textiles and Industries Ltd
- Andhra Paper Ltd
- Emami Paper Mills Ltd
- ITC Limited
- Kuantum Papers Ltd
|
By Raw Material
|
By Application
|
By Region
|
- Waste & Recycled Paper
- Wood
- Agro Residues
|
- Writing & Printing Paper
- Paperboard & Packaging
- Newsprint & Specialty Paper
|
- North India
- East India
- West India
- South India
|
Report Scope:
In this report, the India Paper & Paper Products Market has been segmented into the following categories, in addition to the industry trends which have also been detailed below:
-
India Paper & Paper Products Market, By Raw Material:
-
Waste & Recycled Paper
-
Wood
-
Agro Residues
-
India Paper & Paper Products Market, By Application:
-
Writing & Printing Paper
-
Paperboard & Packaging
-
Newsprint & Specialty Paper
-
India Paper & Paper Products Market, By Region:
-
North India
-
East India
-
West India
-
South India
Competitive Landscape
Company Profiles: Detailed analysis of the major companies present in the India Paper & Paper Products Market.
Available Customizations:
India Paper & Paper Products Market report with the given market data, TechSci Research offers customizations according to a company's specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to five).
India Paper & Paper Products Market is an upcoming report to be released soon. If you wish an early delivery of this report or want to confirm the date of release, please contact us at sales@techsciresearch.com