|
Key Insights
|
Details
|
|
Forecast Period
|
2027-2031
|
|
Market Size (2025)
|
USD 2.07 Billion
|
|
CAGR (2026-2031)
|
9.81%
|
|
Fastest Growing Segment
|
Above 100G
|
|
Largest Market
|
South
|
|
Market Size (2031)
|
USD 3.63 Billion
|
Market Overview
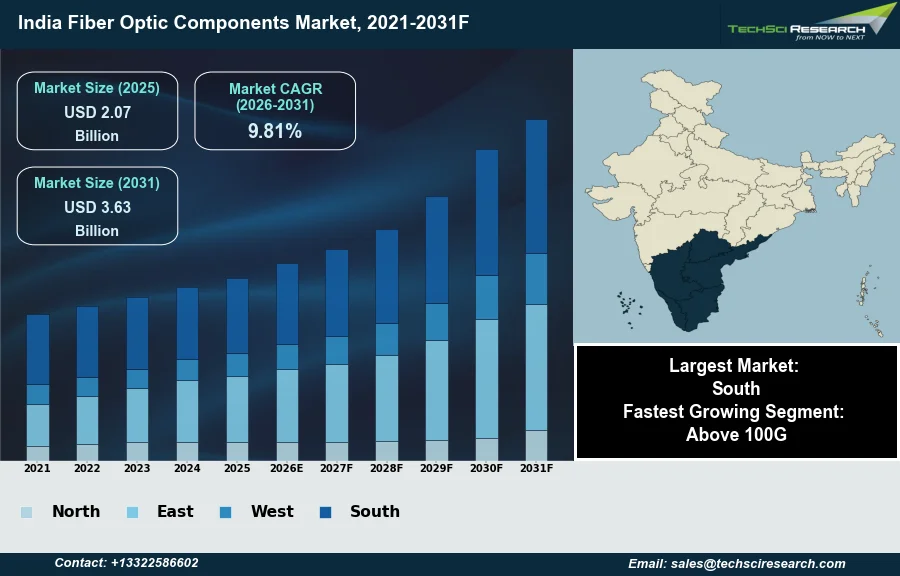
The India Fiber Optic Components Market is expected to grow from USD 2.07 Billion in 2025 to USD 3.63 Billion by 2031 at a 9.81% CAGR. Fiber optic components encompass critical elements such as optical fibers, cables, connectors, transceivers, and optical amplifiers, which collectively form the backbone of high-speed data transmission networks. The market in India is fundamentally driven by escalating demand for high-bandwidth connectivity, increasing internet penetration, and smartphone adoption. Government initiatives like BharatNet and the nationwide 5G rollout significantly bolster demand for fiber optic infrastructure. According to the India Brand Equity Foundation, referencing the Telecom Regulatory Authority of India, gross telecom revenue in India rose from USD 39.22 billion in FY24 to USD 43.42 billion in FY25, indicating robust sector expansion.
Despite this robust growth, the India Fiber Optic Components Market faces challenges, notably the substantial capital expenditure required for laying extensive fiber optic networks and establishing component manufacturing facilities. This investment, coupled with complexities in acquiring right-of-way permissions and managing diverse geographical factors, can impede network expansion and market proliferation.
Key Market Drivers
5G Rollout and Densification Driving Fiber Optic Demand
The extensive rollout and densification of 5G networks represent a primary impetus for the India Fiber Optic Components Market. The next-generation cellular technology necessitates a robust and pervasive fiber optic infrastructure to deliver high data speeds and ultra-low latency, which are crucial for advanced applications. This expanding infrastructure directly increases demand for optical fibers, cables, and related components for backhaul and front-haul connectivity. According to the Department of Telecommunications (India), in June 2024, India had deployed approximately 448.7 thousand 5G base transceiver stations across the nation, underscoring the significant build-out requiring extensive fiber optic support. The ongoing deployment further necessitates fiber densification to support wider coverage and enhanced network capacity, ensuring seamless connectivity for a growing subscriber base.
Data Center Expansion and Digital Growth Boost Fiber Optic Component Demand
Simultaneously, the rapid growth of data center deployments in India significantly boosts the demand for fiber optic components. As digital transformation accelerates, driven by cloud computing, artificial intelligence workloads, and increasing data consumption, the need for high-capacity, low-latency interconnections within and between data centers becomes critical. This surge in data center construction and expansion requires substantial investment in fiber optic cabling and transceivers to manage vast amounts of data traffic efficiently. According to Crisil Ratings, in November 2026, India's data center industry is poised to attract investments of more than ₹3 trillion over the next four financial years to increase installed capacity. This robust investment in data center infrastructure directly translates into heightened demand for advanced fiber optic components. Furthermore, the overall digital landscape is expanding significantly; according to the Ministry of Communications, in March 2024, India's total internet subscriber base reached 954.40 million, reflecting a broad market necessitating underlying high-speed fiber connectivity.
Download Free Sample Report
Key Market Challenges
Capital costs constrain fiber optic deployment and domestic manufacturing.
The India Fiber Optic Components Market faces a significant impediment due to the substantial capital expenditure necessary for deploying extensive fiber optic networks and establishing domestic manufacturing capabilities. The high upfront investment costs involved in trenching, laying cables, and acquiring advanced machinery for component production directly impact the financial viability of expansion projects. This considerable financial outlay can deter potential investors and limit the pace at which new infrastructure can be developed, particularly in rural or remote areas where the return on investment may be slower.
Significant capex plans but restrained market growth.
Such substantial capital requirements present a persistent challenge to market proliferation. According to the India Brand Equity Foundation, independent tower companies were projected to spend approximately INR 21,000 crore (USD 2.42 billion) between FY2025 and FY2026 to expand rural networks and enhance service quality in urban areas. Despite these significant investments in infrastructure, the overall high expenditure for network rollout and establishing advanced manufacturing facilities restricts broader market growth, directly affecting the demand trajectory for fiber optic components.
Key Market Trends
AI-driven advancements spur demand for high-capacity fiber optic components
The India Fiber Optic Components Market is notably influenced by significant advancements in fiber optic technology, particularly those catering to the demands of artificial intelligence infrastructure and high-speed data transmission. These innovations involve developing more efficient and high-capacity fiber and cable solutions capable of handling intensive data workloads. The direct influence on the market is evident in the burgeoning demand for these specialized components. According to The Financial Express, October 2026, India's exports of optical fibers, fiber bundles, and cables surged 158% year-on-year to $483 million in April-August of 2026-27, driven by the global AI investment boom, highlighting the market's response to these technological advancements.
Expansion of domestic manufacturing strengthens supply resilience in fiber optics
Concurrently, a pivotal trend is the strengthening of domestic fiber optic component manufacturing within India. This emphasis on local production, often supported by government initiatives, aims to reduce reliance on imports, foster indigenous innovation, and enhance supply chain resilience. Domestic manufacturers are investing substantially to boost their production capabilities to meet both national and international demand for optical components. For instance, according to ET Telecom, September 2026, HFCL increased its capital expenditure to ₹1,800 crore to significantly expand production capacity for optical fibre by an additional 46 lakh fibre kilometers per annum. This strategic expansion directly impacts the market by ensuring a more robust and self-reliant supply of critical fiber optic infrastructure.
Segmental Insights
Expansion of the Above-100G Segment Driven by 5G Rollout, Data Centers, and Government Initiatives
The India Fiber Optic Components Market is experiencing significant expansion, with the "Above 100G" segment demonstrating rapid growth. This accelerated demand is primarily driven by the extensive rollout of 5G networks across India, which necessitates robust, high-bandwidth fiber infrastructure to support ultra-low latency and high-speed data transmission. Concurrently, the booming data center market, fueled by increasing cloud adoption, the deployment of artificial intelligence workloads, and data localization policies, demands increasingly dense and high-capacity fiber optic components for massive data transfer within and between facilities. Furthermore, ongoing government initiatives, including the Digital India program and BharatNet, are consistently enhancing the nation's digital infrastructure, thereby escalating the need for advanced fiber optic solutions capable of supporting these higher data rates.
Regional Insights
South India Leads the Fiber Optic Components Market Driven by Tech Hubs and Government Initiatives
South India leads the India Fiber Optic Components Market, primarily driven by its established technology ecosystems in states such as Karnataka, Telangana, and Tamil Nadu. This region benefits from a significant concentration of information technology companies, data centers, and a thriving startup landscape, generating substantial demand for high-capacity fiber optic networks essential for cloud computing, enterprise connectivity, and advanced mobile services. Furthermore, ongoing smart city and industrial corridor projects, coupled with state governments' active support for central initiatives like BharatNet and Digital India by the Department of Telecommunications, further accelerate the need for robust fiber-based communication infrastructure, fostering continuous market expansion.
Recent Developments
-
In December 2024, Tejas Networks, an Indian telecommunications equipment manufacturer, was selected as the broadband equipment supplier for the BharatNet Last Mile Connectivity project in Tamil Nadu. The company committed to supplying its GPON OLT, ONT, and Management System for this state-led initiative. This significant collaboration, with Polycab India Limited as the Master System Integrator, aims to extend affordable high-speed connectivity to numerous government institutions, public health centers, and schools across rural Tamil Nadu. Tejas Networks’ involvement directly strengthens the India Fiber Optic Components Market by providing essential infrastructure for national digital transformation efforts.
-
In September 2024, HFCL, an Indian telecommunications company, showcased its latest high-density blown fiber solutions, including Compact Fibre Units, a 36F Fibre Blown Nano family cable, and a new Openreach-approved 1F Aerial Drop Cable. These innovations are designed to facilitate more efficient, economical, and sustainable connectivity. The expanded Nano Thin microcable product line also introduced an 864 fiber cable, boasting a record fiber packing density, which is crucial for maximizing fiber capacity in microducts. This product development by an Indian company directly contributes to advancing fiber optic component capabilities within the India Fiber Optic Components Market, supporting increased data traffic and network deployments.
-
In July 2024, STL (Sterlite Technologies), a prominent Indian optical and digital solutions company, unveiled advanced high-density optical fiber cables at a major industry event. Among these were 864F Micro Cables, capable of packing 864 fibers within a small diameter, utilizing STL's bend-insensitive 200-micron fiber. Additionally, an Intelligently Bonded Ribbon (IBR) Armored cable was introduced, featuring a compact design for easier installation and improved splicing outcomes. These product launches by a leading Indian firm underscore ongoing innovation in high-capacity fiber optic components, poised to enhance network scalability and efficiency within the India Fiber Optic Components Market.
-
In May 2024, R&M, a global provider of infrastructure solutions for data and communications networks, inaugurated a new fiber optic plant in Bagaluru, located in northern Bangalore, India. This strategic expansion involved the relocation of an existing facility and a subsequent investment in new production lines, significantly boosting the company's manufacturing capacity within the region. The plant's primary objective is to cater to the growing demand for fiber optic components from data centers and 5G service users. This development marks a substantial investment in local manufacturing capabilities for the India Fiber Optic Components Market.
Key Market Players
- Sterlite Technologies Ltd
- Finolex Cables Ltd
- Corning
- TE Connectivity
- Sumitomo Electric
- Accelink Technologies
- CommScope
- Fujikura
- Broadcom
- Lumentum
|
By Type
|
By Data Rate
|
By Application
|
By Region
|
- Fiber Optic Cables
- Fiber Optic Splitters
- Fiber Optic Transceivers
- Fiber Optic Amplifiers
- Fiber Optic Circulators
- Fiber Optic Connectors & Others
|
- 10G
- 40G
- 100G and Above 100G
|
- Distributed Sensing
- Analytical and Medical Equipment
- Lighting
- Communications & Others
|
- North India
- East India
- West India
- South India
|
Report Scope:
In this report, the India Fiber Optic Components Market has been segmented into the following categories, in addition to the industry trends which have also been detailed below:
-
India Fiber Optic Components Market, By Type:
-
Fiber Optic Cables
-
Fiber Optic Splitters
-
Fiber Optic Transceivers
-
Fiber Optic Amplifiers
-
Fiber Optic Circulators
-
Fiber Optic Connectors & Others
-
India Fiber Optic Components Market, By Data Rate:
-
10G
-
40G
-
100G and Above 100G
-
India Fiber Optic Components Market, By Application:
-
Distributed Sensing
-
Analytical and Medical Equipment
-
Lighting
-
Communications & Others
-
India Fiber Optic Components Market, By Region:
-
North India
-
East India
-
West India
-
South India
Competitive Landscape
Company Profiles: Detailed analysis of the major companies present in the India Fiber Optic Components Market.
Available Customizations:
India Fiber Optic Components Market report with the given market data, TechSci Research offers customizations according to a company's specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to five).
India Fiber Optic Components Market is an upcoming report to be released soon. If you wish an early delivery of this report or want to confirm the date of release, please contact us at sales@techsciresearch.com