|
Key Insights
|
Details
|
|
Forecast Period
|
2027-2031
|
|
Market Size (2025)
|
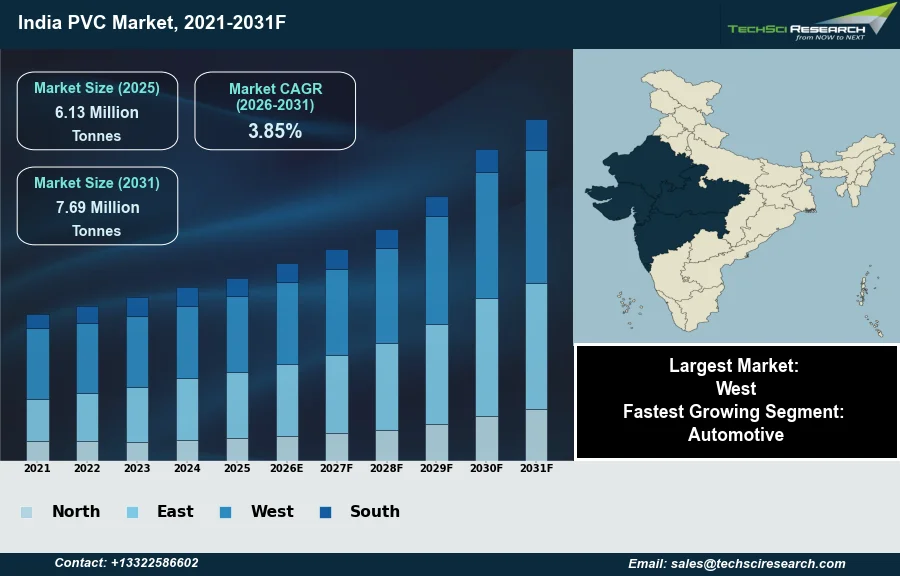
6.13 Million Tonnes
|
|
CAGR (2026-2031)
|
3.85%
|
|
Fastest Growing Segment
|
Automotive
|
|
Largest Market
|
West
|
|
Market Size (2031)
|
7.69 Million Tonnes
|
Market Overview
The India PVC Market is expected to grow from 6.13 Million Tonnes in 2025 to 7.69 Million Tonnes by 2031 at a 3.85% CAGR. Polyvinyl chloride (PVC) is a versatile thermoplastic polymer produced from vinyl chloride monomers. The growth of the Indian PVC market is primarily propelled by robust demand from the construction sector, driven by urbanization and government infrastructure development programs. The expanding agricultural sector, particularly for irrigation applications, and the packaging industry further contribute to this sustained market expansion.
A significant challenge impeding market expansion is the volatility of crude oil prices, which directly influences the cost of key raw materials like ethylene dichloride and vinyl chloride monomer, thereby impacting production costs and overall market stability. Despite these challenges, according to the Plastics Export Promotion Council, India's exports of plastic pipes and fittings, a major PVC application, demonstrated a substantial 40.2% growth in September 2026.
Key Market Drivers
Infrastructure investment driving PVC demand
The expanding infrastructure development and investments in India are a primary catalyst for the robust growth of the PVC market. Extensive government initiatives aimed at modernizing urban and rural infrastructure, including roads, railways, ports, and housing projects, significantly escalate the demand for PVC products such as pipes and fittings, cables, and window profiles. These development programs necessitate durable, cost-effective, and long-lasting materials, where PVC's superior properties make it an ideal choice. According to Vision IAS, in January 2026, the Government of India's capital outlay rose by nearly 89%, from ₹5.92 lakh crore in FY22 to ₹11.21 lakh crore in FY26, reflecting substantial investment in foundational projects that directly drive PVC consumption.
Agriculture-driven irrigation demand propels PVC market
Concurrently, the increasing agricultural demand for irrigation and water management systems further propels the Indian PVC market. With a significant portion of India's economy reliant on agriculture, the need for efficient water distribution solutions is critical for enhancing crop yield and conserving water resources. PVC pipes and fittings are extensively utilized in micro-irrigation systems, including drip and sprinkler installations, due to their corrosion resistance, lightweight nature, and ease of installation. According to IndianPetroChem.com, PVC demand stemming from agriculture and construction for irrigation and water distribution pipes grew by an annual rate of 6.2% from 2019-20 to 2025-26. This sustained demand from critical sectors underpins the broader market expansion. Overall, according to the Plastics Export Promotion Council, in FY 2024–25, India's plastics exports experienced an impressive 8% growth, reaching a total value of USD 12.5 billion.
Download Free Sample Report
Key Market Challenges
Crude Oil Volatility Impedes India PVC Expansion
The volatility of crude oil prices presents a significant impediment to the expansion of the India PVC market. Crude oil serves as a foundational component in the production of crucial PVC raw materials, such as ethylene dichloride and vinyl chloride monomer. Fluctuations in crude oil prices directly translate into unpredictable and often higher costs for these key inputs, thereby increasing overall production expenses for PVC manufacturers. This instability makes long-term planning and investment challenging, as producers face uncertainty regarding their operational margins and the overall stability of the market.
Rising Input Costs and Profitability Pressure in PVC Manufacturing
This cost pressure directly impacts the profitability of PVC manufacturing companies, potentially leading to reduced production or slower investment in capacity expansion. According to industry estimates cited by The Economic Times, input costs for plastic producers, including those manufacturing PVC, jumped by 50 to 60 percent in March 2026, driven by a steep increase in the prices of key crude-linked polymers. Furthermore, PVC prices rose approximately ₹30 per kilogram in March 2026 alone, with a total increase of nearly ₹40 per kilogram in 2026. Such substantial increases compel manufacturers to either absorb higher costs, compressing profit margins, or pass them on to consumers, which can dampen demand and restrain market growth.
Key Market Trends
Sustainability shift and regulatory push in Indian PVC
The Indian PVC market is experiencing a notable shift towards sustainable innovations and eco-friendly formulations, driven by increasing environmental consciousness and stricter regulatory frameworks. Manufacturers are investing in developing greener alternatives, such as PVC products with reduced reliance on heavy metals and increased integration of recycled content. This trend is further propelled by government mandates aiming to foster a circular economy within the plastics sector. According to the Ministry of Environment, Forest and Climate Change, rigid plastics are targeted to increase recycled content from 30% in FY 2025–26 to 60% by FY 2028–29. This directly influences PVC production practices and material composition.
Diversification into non-construction sectors and value-added PVC products
Beyond traditional applications in construction and agriculture, the India PVC market is increasingly diversifying into non-construction sectors, expanding its revenue streams and reducing reliance on a few dominant industries. This includes greater adoption of PVC in automotive components, medical devices, packaging films, and consumer goods, where its durability, cost-effectiveness, and adaptability are highly valued. The focus on value-added products in these emerging areas signifies a strategic pivot for manufacturers. For instance, according to the Indian Brand Equity Foundation (IBEF), citing the Plastics Export Promotion Council, plastic films and sheets, a key component in packaging, demonstrated a significant growth of 36.4% during April-July 2026. This expansion into diverse end-use industries is crucial for the sustained growth and resilience of the Indian PVC market.
Segmental Insights
Automotive Sector Drives Rapid Growth in the India PVC Market
The Automotive segment is emerging as the fastest-growing sector within the India PVC Market. This rapid expansion is primarily driven by the increasing integration of PVC in modern vehicle manufacturing, particularly to support lightweighting initiatives that enhance fuel efficiency and reduce emissions. Furthermore, the burgeoning electric vehicle market in India significantly boosts PVC demand for applications such as battery housing, specialized wiring insulation, and thermal management components, leveraging PVC's cost-effectiveness and versatile properties. Government encouragement for domestic manufacturing and electric vehicle adoption, alongside rising overall vehicle production, collectively underpins this segmental growth.
Regional Insights
Western Region PVC Leadership Fueled by Industrial Hubs, Infrastructure Investment, and Urban Growth
The Western region stands as the dominant force within the India PVC market, primarily due to its robust industrial infrastructure. States such as Maharashtra and Gujarat serve as significant manufacturing hubs, housing numerous production units that drive substantial demand for PVC across a broad spectrum of applications, including the critical construction, automotive, and packaging sectors. Furthermore, the region benefits from extensive government investments in infrastructure projects, coupled with rapid urbanization in major cities like Mumbai and Ahmedabad, which collectively fuel the need for PVC in housing and commercial developments. This dominance is further strengthened by better access to essential raw materials and well-established supply chains, which collectively enhance manufacturing efficiency and reduce logistics costs.
Recent Developments
-
In August 2025, DCW Ltd, a specialty chemical manufacturer, successfully commissioned the initial phase of its Chlorinated Polyvinyl Chloride (CPVC) capacity expansion project. This milestone involved adding 20,000 metric tonnes of new capacity, effectively doubling the company's total CPVC production capacity to 40,000 metric tonnes. The commissioning occurred ahead of its original schedule, with the new capacity expected to achieve full utilization promptly. This expansion was part of a broader capital investment plan aimed at increasing CPVC capacity and was intended to meet the growing demand for high-performance CPVC in applications such as plumbing and industrial piping within the Indian market.
-
In May 2025, Astral Limited announced that it had received ISI approval for its Oriented Polyvinyl Chloride (O-PVC) products. This certification marked a readiness for the company to commence the sale of these specialized O-PVC products in the Indian market. The approval signified that Astral Limited's O-PVC offerings met the quality and safety standards mandated for products within India. This development was a strategic step for the company, expanding its product portfolio and strengthening its position in the competitive PVC pipes and fittings segment, catering to various infrastructure and construction applications.
-
In March 2025, The Supreme Industries Limited, a prominent Indian manufacturer, entered into a Memorandum of Understanding to acquire the Indian piping business of Wavin India, a subsidiary of the Orbia Group. The acquisition, valued at USD 30 million, encompassed Wavin's manufacturing units and provided Supreme Industries with exclusive access to Wavin's advanced water management technology for India and other SAARC nations. This strategic collaboration was designed to reinforce Supreme Industries' leadership position within the polyvinyl chloride (PVC) piping sector. The move aimed to significantly enhance the company’s market presence, particularly in the North and South Indian regions.
-
In August 2024, Reliance Industries announced significant plans to expand its production capabilities within the Indian PVC market. The company intended to establish new polyvinyl chloride (PVC) and chlorinated polyvinyl chloride (CPVC) manufacturing facilities at its Dahej and Nagothane sites. These new facilities were projected to have a combined annual production capacity of 1.5 million tonnes. The strategic move aimed to address the increasing domestic demand for PVC and CPVC products across various sectors. Commercial operations for these integrated facilities were expected to commence in the financial year 2026-2027, contributing to a reduction in India's reliance on imported PVC materials.
Key Market Players
- Reliance Industries Ltd
- Finolex Industries Ltd
- Chemplast Sanmar Ltd
- DCM Shriram Ltd
- Supreme Industries Ltd
- Astral Ltd
- Jindal Poly Films Ltd
- Prince Pipes and Fittings Ltd
- Pidilite Industries Ltd
- Shin-Etsu Chemical Company Ltd
|
By Product Type
|
By End Use
|
By Region
|
|
|
- Building & Construction
- Packaging
- Automotive
- Electrical & Electronics
- Others
|
- North India
- East India
- West India
- South India
|
Report Scope:
In this report, the India PVC Market has been segmented into the following categories, in addition to the industry trends which have also been detailed below:
-
India PVC Market, By Product Type:
-
India PVC Market, By End Use:
-
Building & Construction
-
Packaging
-
Automotive
-
Electrical & Electronics
-
Others
-
India PVC Market, By Region:
-
North India
-
East India
-
West India
-
South India
Competitive Landscape
Company Profiles: Detailed analysis of the major companies present in the India PVC Market.
Available Customizations:
India PVC Market report with the given market data, TechSci Research offers customizations according to a company's specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to five).
India PVC Market is an upcoming report to be released soon. If you wish an early delivery of this report or want to confirm the date of release, please contact us at sales@techsciresearch.com